
OSS VAT: Selling to the EU Without Registering Everywhere
The €10,000 threshold, One Stop Shop registration, the destination country rate and what is still invoiced in Portugal. A guide for online shops.
You sell from Portugal and orders start arriving from Spain, France, Germany. The question always comes in the same order: which VAT do I charge? And right after: who do I pay it to?
The short answer: above a certain volume you charge the buyer's country rate and you pay it all through a single return filed in Portugal. That mechanism is the OSS, the One Stop Shop.
The €10,000 threshold
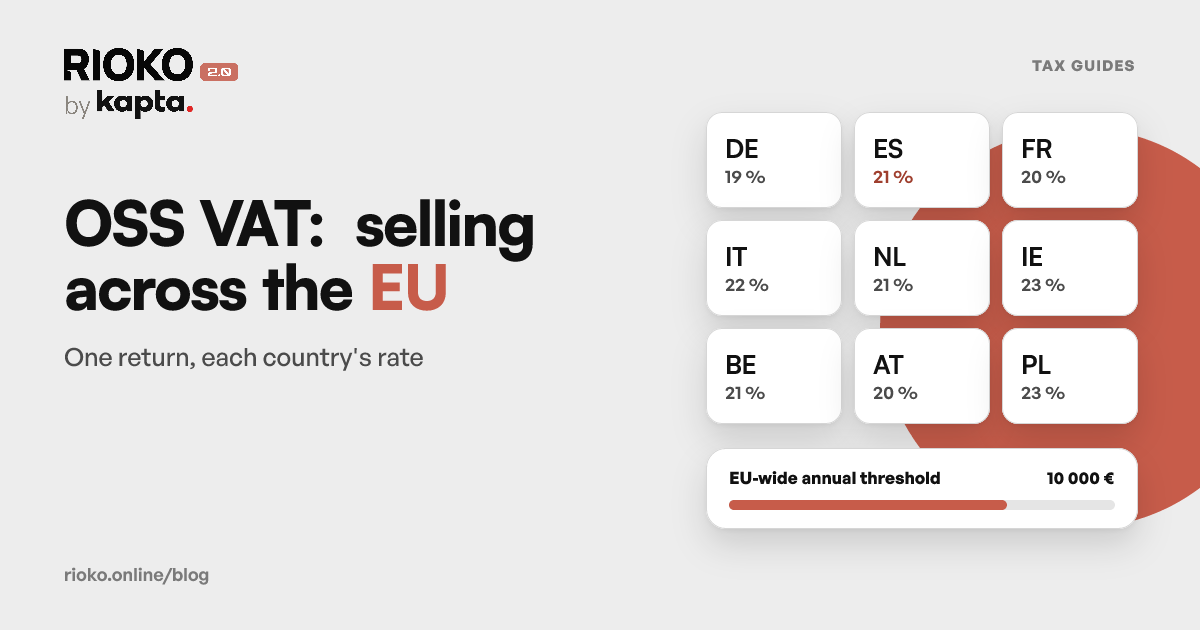
Since 1 July 2021 there is a single threshold for the whole European Union: €10,000 per calendar year, adding up all distance sales to consumers in all EU countries, plus electronic, telecommunications and broadcasting services.
- Below €10,000 you may keep charging Portuguese VAT to everyone, as though the sales were domestic. Simple, and perfectly legal.
- Above €10,000 you start charging the destination country rate, from the sale that crosses the threshold. Not the following year: that sale.
The threshold is aggregate, not per country. €4,000 to Spain plus €7,000 to France is €11,000 and the threshold is crossed, even though no single country came close.
You may opt to apply destination rates before reaching the threshold. For anyone selling mostly into countries with lower rates than Portugal it is worth weighing with your accountant. The option binds you for two calendar years.
What OSS solves, and what it does not
Under OSS the VAT rate is the buyer's country's, but it is filed in a single Portuguese return.Without OSS, charging destination rates meant registering for VAT in every country you sold into. With OSS you register once in Portugal and file everything in one quarterly return; the tax authority distributes the VAT to each member state.
What does not go through OSS:
- Sales to businesses with a valid VAT number in another member state. That is a no-VAT sale to an EU business, not OSS.
- Sales outside the EU. Export, 0%, code
M05. - Domestic Portuguese sales. They go in the ordinary periodic return, as always.
- Sales shipped from another country, for example stock in a German warehouse. Those have their own rules and may well require local registration.
Registering: where and how
Registration is done on the Portal das Finanças, in the One Stop Shop (OSS) area, under the Union scheme. Once registered:
- You file a quarterly return, by the end of the month following the quarter.
- You pay the total in a single transfer, using the reference the return generates.
- You keep filing your ordinary periodic return for domestic sales.
The registration takes effect from the start of the following quarter, except for someone registering because they have just crossed the threshold: then it applies from the sale that crossed it, provided the registration is made by the 10th of the following month.
The standard rates across the 27
The rate you apply is the buyer's country rate for the product in question. These are the standard rates; many products carry their own reduced rates in each country, and those vary considerably.
| Country | Rate | Country | Rate | Country | Rate |
|---|---|---|---|---|---|
| Austria | 20% | Estonia | 24% | Latvia | 21% |
| Belgium | 21% | Finland | 25.5% | Lithuania | 21% |
| Bulgaria | 20% | France | 20% | Luxembourg | 17% |
| Croatia | 25% | Germany | 19% | Malta | 18% |
| Cyprus | 19% | Greece | 24% | Netherlands | 21% |
| Czechia | 21% | Hungary | 27% | Poland | 23% |
| Denmark | 25% | Ireland | 23% | Portugal | 23% |
| Slovakia | 23% | Italy | 22% | Romania | 21% |
| Slovenia | 22% | Spain | 21% | Sweden | 25% |
Standard rates in November 2026. Reduced rates vary by country and by product: confirm them in the European Commission's table.
The invoice is still Portuguese
The point that confuses most people: applying Spanish VAT does not mean issuing a Spanish invoice.
The document still comes out of your Portuguese certified software, in your series filed with the tax authority, with ATCUD and QR Code, and it enters your SAF-T file. What changes is the rate applied on the line and, at quarter end, where that VAT is declared.
That is why a shop registered for OSS does not need a series per country: it needs software that can apply the right rate per line.
Madeira and the Azores are not OSS
A domestic case that gets confused with this one: a customer living in Madeira or the Azores is not an intra-EU distance sale. It is Portugal, at the regional rate (22% and 16% at the standard level). It does not go through OSS; it goes in the ordinary periodic return.
Common mistakes
- Counting the threshold per country. It is €10,000 added up, for the whole EU.
- Not watching the threshold during campaigns. A Black Friday can take you past €10,000 mid-week.
- Applying destination rates to businesses. If the buyer is a business with a valid VIES number, the sale goes out at 0%, not OSS.
- Forgetting shipping. In distance sales to EU consumers, the destination country's rate applies to the goods and to shipping (binding ruling 27240).
- Charging 23% to everyone after crossing the threshold. You are overcharging the customer and under-declaring to their country. Both sides are a problem.
- Registering for OSS and leaving the software on a single rate. The registration on its own changes not one invoice.
How Rioko helps
In Rioko, OSS is a registration you declare, not a rule you write. On connections to InvoiceXpress, Moloni and Moloni ON, you switch it on once and from then on each sale is classified by the buyer's country and status: a consumer in the EU gets their country's rate, a business confirmed in VIES goes out at 0%, outside the EU gets export. In TOConline, you switch OSS on in the integration and each sale to a consumer in another EU country goes out in that country's OSS series, which has to be created and filed with the tax authority (guide).
When the source has already calculated tax, as Shopify and Stripe Tax do, the document total has to match what the person actually paid. With the OSS registration and VAT included both on, a consumer in another EU country gets that country's standard rate, even if the source charged a different one: Rioko recalculates the net and the VAT and keeps the total. Without the registration, and on Shopify connections to InvoiceXpress, the rate the source charged stands.
If you also sell to businesses, read Invoicing EU businesses without VAT: VIES, M16 and M40 next. If you are still unsure which code goes on a zero-rated line, the table is in Exemption codes M01–M99.
See how Rioko invoices sales from Shopify, Stripe, Lodgify, Easypay and EuPago, and check the pricing.
To see where the rate on each document comes from, read how Rioko decides the VAT.
The OSS changes planned from 2027 are in the article on ViDA.
Sources
Frequently asked questions
Is the €10,000 threshold per country or in total?
In total. You add up every distance sale to consumers in every EU country in the calendar year. €4,000 to Spain plus €7,000 to France already crosses it.
From which sale do I apply the destination country's rate?
From the sale that crosses €10,000. Not the following year: that sale.
Do I have to register for OSS?
No. Above the threshold you can use OSS or register for VAT in each destination country. OSS avoids those registrations and puts everything in one return in Portugal.
Can I apply the destination rate before reaching the threshold?
You can, by opting in, and the option binds you for two calendar years. It is worth weighing with your accountant.
I am registered for OSS. Do I still issue Portuguese invoices?
Yes. The document comes out of your Portuguese certified software, in your filed series, with ATCUD and QR Code. What changes is the rate applied and where that VAT is declared.
Does shipping take the destination country's rate?
Yes. In distance sales to EU consumers, the tax authority applies the destination country's rate to the goods and to shipping (binding ruling 27240).
Do sales to businesses in other countries go through OSS?
No. A sale to a business with a VAT number confirmed in VIES goes out at 0% and is reported in the recapitulative statement.
What about sales to Madeira and the Azores?
Those are domestic sales at the regional rate, not intra-EU distance sales. They go in the ordinary periodic return.
How often is the OSS return filed?
Quarterly, by the end of the month following the quarter, and it does not replace the periodic return for domestic sales.
Do I need different series per country?
No. The invoice stays Portuguese, in your series filed with the tax authority. What has to change is the rate on each line.
Still have questions
Write the question. It reaches a person, not a form.