
Invoicing EU Businesses Without VAT: VIES, M16 and M40
Selling to businesses in other EU countries: VIES validation, M16 for goods, M40 for services, what to write on the invoice and the recapitulative statement.
A German company buys €2,000 of product from you. They ask for an invoice with their VAT number. Do you charge VAT?
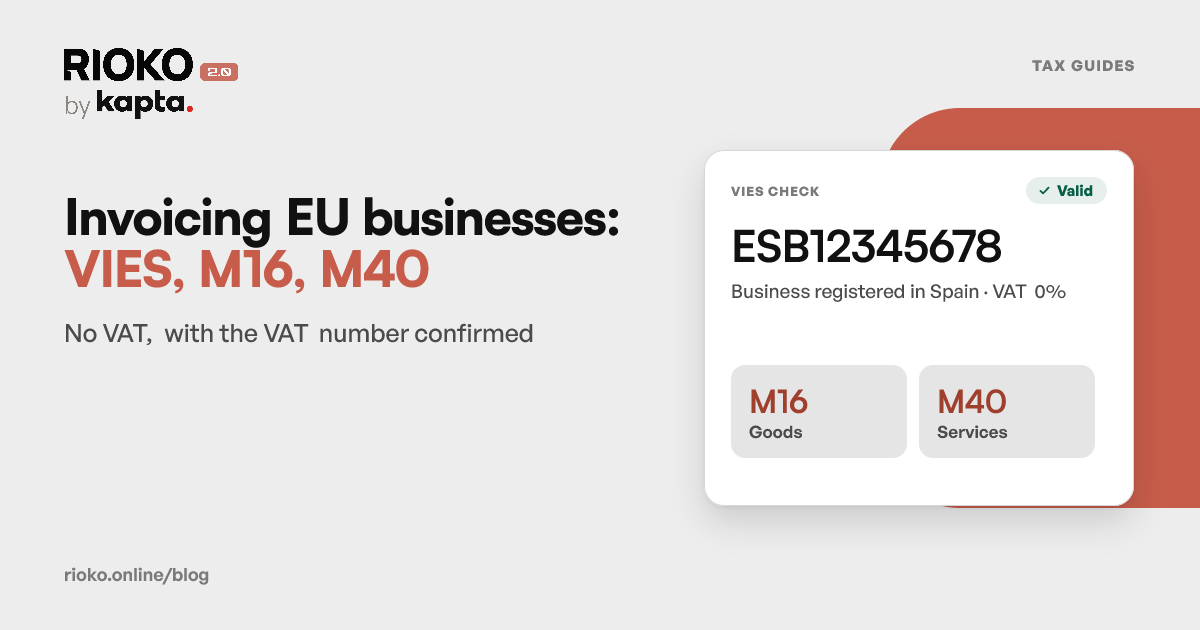
No, provided you can prove they really are a taxable person registered in another member state. The VAT does not disappear: the buyer handles it in their own country. For goods it is an exemption under article 14 of the RITI (M16); for services it is reverse charge (autoliquidação), with M40.
The key word is prove. Not "the customer typed a number into the checkout".
The sequence, and the step nobody may skip
Selling without VAT to an EU business: five steps, and the second is the one nobody may skip.Step 1: the number comes with its country
An intra-EU VAT number carries the country prefix: ES for Spain, FR for France, DE for Germany. B12345678 on its own is not enough; ESB12345678 is the number.
Many checkouts collect the number without the prefix, because the field was designed for Portuguese customers. If you are going to sell to EU businesses, the field has to accept and store the prefix.
Step 2: VIES, and only VIES
VIES is the European VAT number validation system. It is the only place to confirm that a number exists, is active, and belongs to a taxable person registered for intra-EU operations.
Three possible answers, three different consequences:
| VIES answer | What it means | What to do |
|---|---|---|
| Valid | The number exists and is registered for intra-EU operations | Issue at 0%, with the right code |
| Invalid | The number does not exist, or is not registered in VIES | Treat as a consumer: charge VAT (OSS or Portuguese rate) |
| Service unavailable | That country's system did not answer | Do not decide. Wait and retry |
The third case is the treacherous one. "Did not answer" is neither "invalid" nor "valid", and treating it as either issues a document that may be wrong. The correct move is to hold the document and repeat the validation: national VIES services go down frequently and come back on their own.
VIES is not for Portuguese customers. A Portuguese company buying from another Portuguese company is a domestic operation: ordinary Portuguese VAT. And many Portuguese numbers do not even appear in VIES, because only those registered for intra-EU operations are listed.
Step 3: the code, M16 for goods and M40 for services
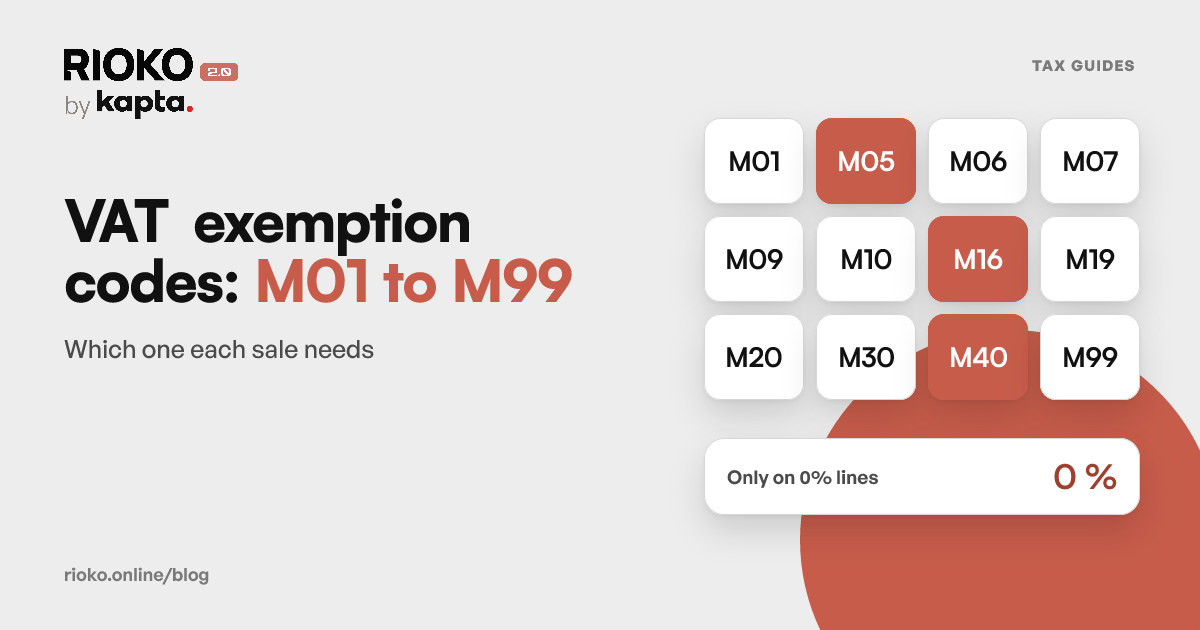
This is where most configurations go wrong. The full table of exemption codes shows the context of both.
| You sell | Legal basis | Code | Typical wording |
|---|---|---|---|
| Goods to an EU business | Article 14 of the RITI | M16 | Isento artigo 14.º do RITI |
| Services to a business abroad | Article 6(6)(a) of the CIVA, read the other way round | M40 | IVA - autoliquidação |
Both come out at 0%, but the legal basis differs, the wording on the invoice differs and the SAF-T file tells them apart. If you sell physical product, it is M16. If you sell access, consultancy, licences or training, it is M40.
A mixed catalogue has to distinguish line by line. There is no single code that covers both.
Step 4: the wording has to be on the document
For services, the invoice has to carry the phrase "IVA - autoliquidação" (article 36(13) of the VAT Code). For goods, it states the reason the tax does not apply: "Isento artigo 14.º do RITI". The tax authority states that in these supplies the buyer reverse-charge mechanism does not operate. In both cases, the buyer's prefixed VAT number has to be visible on the document.
A 0% invoice with no buyer VAT number and no wording cannot be defended in an inspection, however legitimate the sale was. The document has to tell the story on its own.
Step 5: the recapitulative statement
This is the part people discover late: intra-EU supplies have to be reported in a recapitulative statement, on top of the periodic return.
- It is filed on the Portal das Finanças, with each customer's VAT number and the total per customer in the period.
- It is monthly if operations exceed €50,000 in the current quarter or in any of the previous four; otherwise, it follows the frequency of your VAT returns.
- The deadline is the 20th of the month following the period (article 30 of the RITI).
What you report here has to match what your customer reports on the other side. That cross-check is exactly what produces letters from the tax authority when a number is wrong.
Common mistakes
- Accepting the number without validating it. This is the one that costs money: if the number was not valid, the VAT was due, and you are the one paying it, with interest.
- Validating once and never again. A number valid in January can be cancelled by September. For recurring customers, validation is per sale.
- M16 on services. Wrong legal basis in the SAF-T file. It still comes out at 0%, which is what lets the error go unnoticed for years.
- Reverse charge to a consumer. A French individual performs no reverse charge, whatever they typed into the VAT field. That sale carries VAT, and above the threshold it goes through OSS.
- Forgetting the recapitulative statement. The invoice was right and the declaration was never filed.
How Rioko helps
In Rioko, a no-VAT sale to a business is not a box you tick per customer: it is the result of a check. With the option switched on in the integration, the buyer's VAT number is validated in VIES at the time of the sale, and the regime only changes when VIES confirms.
When VIES does not answer, Rioko does not apply 0% on a guess. On Shopify connections to InvoiceXpress, the sale is held and retried on its own. On other connections, the sale keeps the VAT charged and, in InvoiceXpress, a document with a 0% line stays a draft.
The code follows from the nature of what you sell, and the legal wording travels with the document. If you sell through a shop or through payments, the Shopify and Stripe guides show where this fits. If companies buy on Shopify B2B, see also Shopify B2B: invoicing sales to companies. The table of all the reasons is in Exemption codes M01–M99.
See how Rioko invoices sales from Shopify, Stripe, Lodgify, Easypay and EuPago, and check the pricing.
Sources
Frequently asked questions
Is it enough for the customer to say they are a business?
No. You need a VAT number with the country prefix and a "valid" answer from VIES. Without that, the sale is treated as a sale to a consumer and carries VAT.
Is selling goods to an EU business reverse charge?
Not strictly. It is a supply exempt under article 14 of the RITI, with code M16, and the tax authority states that the buyer reverse-charge mechanism does not operate there. The buyer handles the VAT in their own country.
What is the difference between M16 and M40?
M16 applies to goods sold to businesses in another member state. M40 applies to services supplied to taxable persons in another country, under reverse charge. See the full table of codes.
What wording has to be on the invoice?
For services (M40), the phrase IVA - autoliquidação. For goods (M16), the reason for the exemption: Isento artigo 14.º do RITI. In both cases, the buyer's prefixed VAT number has to be on the document.
VIES did not answer. Do I issue anyway?
No. "Service unavailable" is neither "valid" nor "invalid". The right move is to hold the document and retry the validation: national VIES services go down often and come back on their own.
Is VIES any use for Portuguese VAT numbers?
Not for this purpose. A Portuguese business selling to another Portuguese business is a domestic operation with ordinary VAT. Besides, many Portuguese numbers do not appear in VIES at all.
Do I have to validate the VAT number on every sale?
For recurring customers, yes. A number valid in January can be cancelled by September, and the validation is what backs up the sale at 0%.
Beyond the invoice, is there anything to declare?
Yes: the recapitulative statement, with each customer's VAT number and the total per customer, by the 20th of the month after the period. It is monthly if operations exceed €50,000 in the current quarter or in any of the previous four.
The customer is a consumer in another EU country. Does this apply?
No. Without a valid VAT number the sale carries VAT: the Portuguese rate or, above the threshold, their country's rate through OSS.
The buyer is outside the EU. What changes?
VIES only covers the EU. Goods leaving the EU are an export, with code M05 and proof that the goods left.
Still have questions
Write the question. It reaches a person, not a form.